Research note · Checklists
Free healthcare review checklist (plain English)
Why a checklist
Most people do not fail reviews because they are "bad at insurance." They fail because the paperwork is scattered and the questions stay vague. This checklist is meant to make a review concrete.
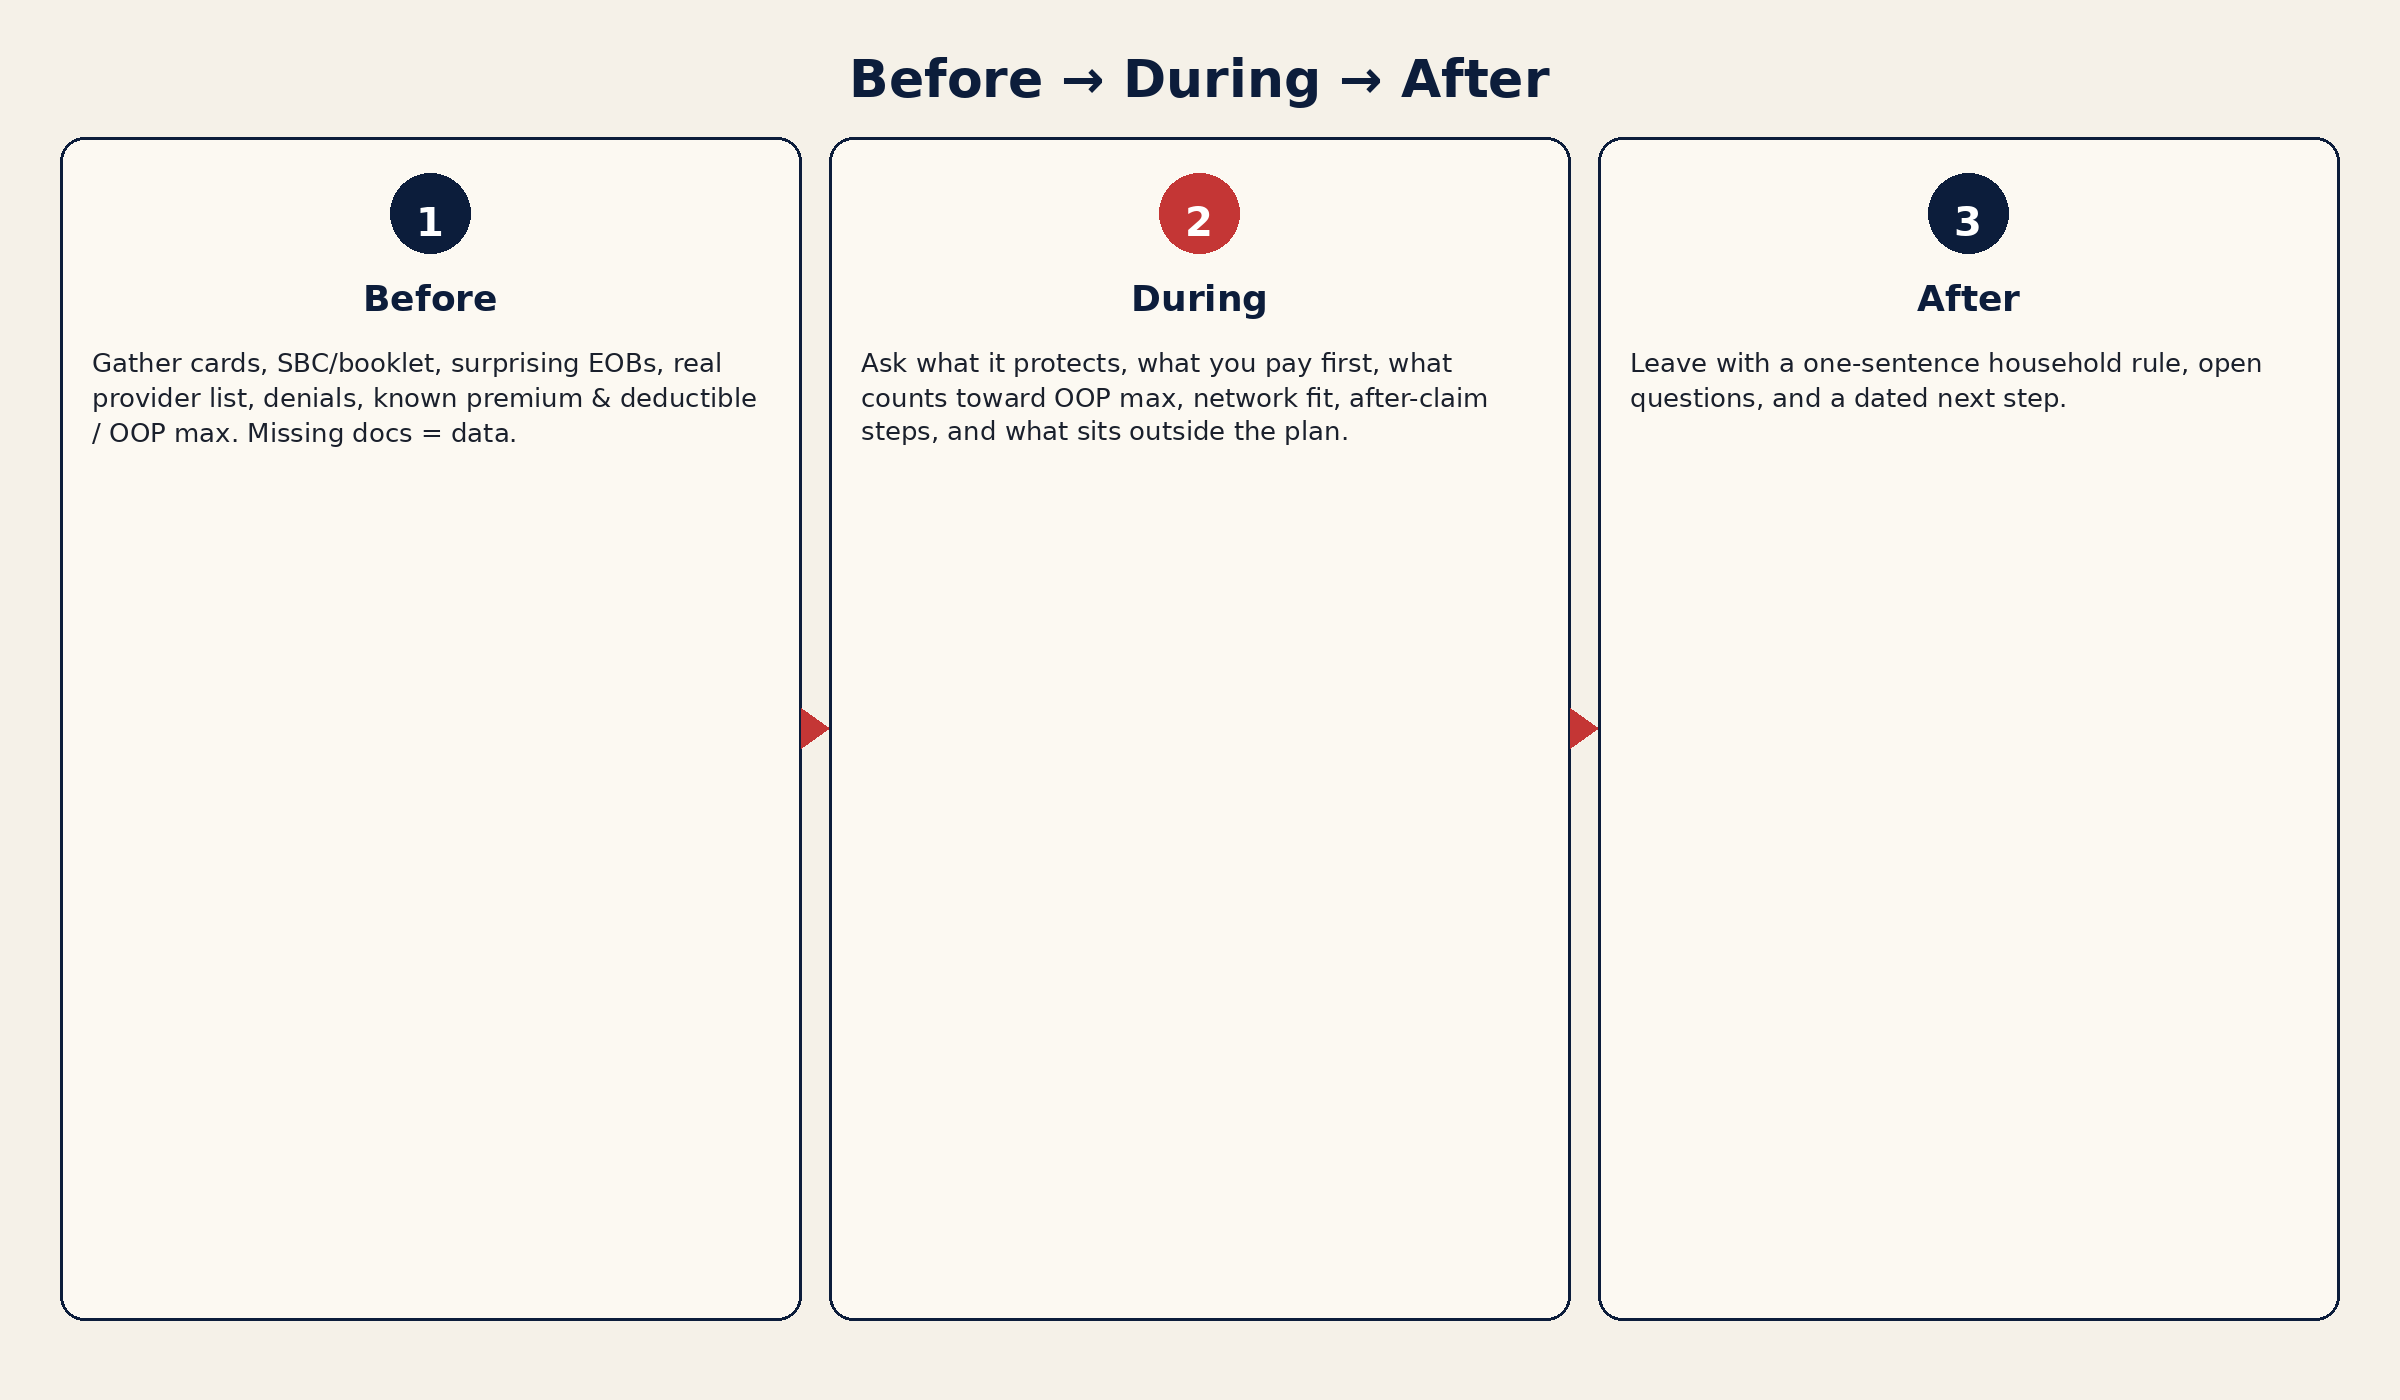
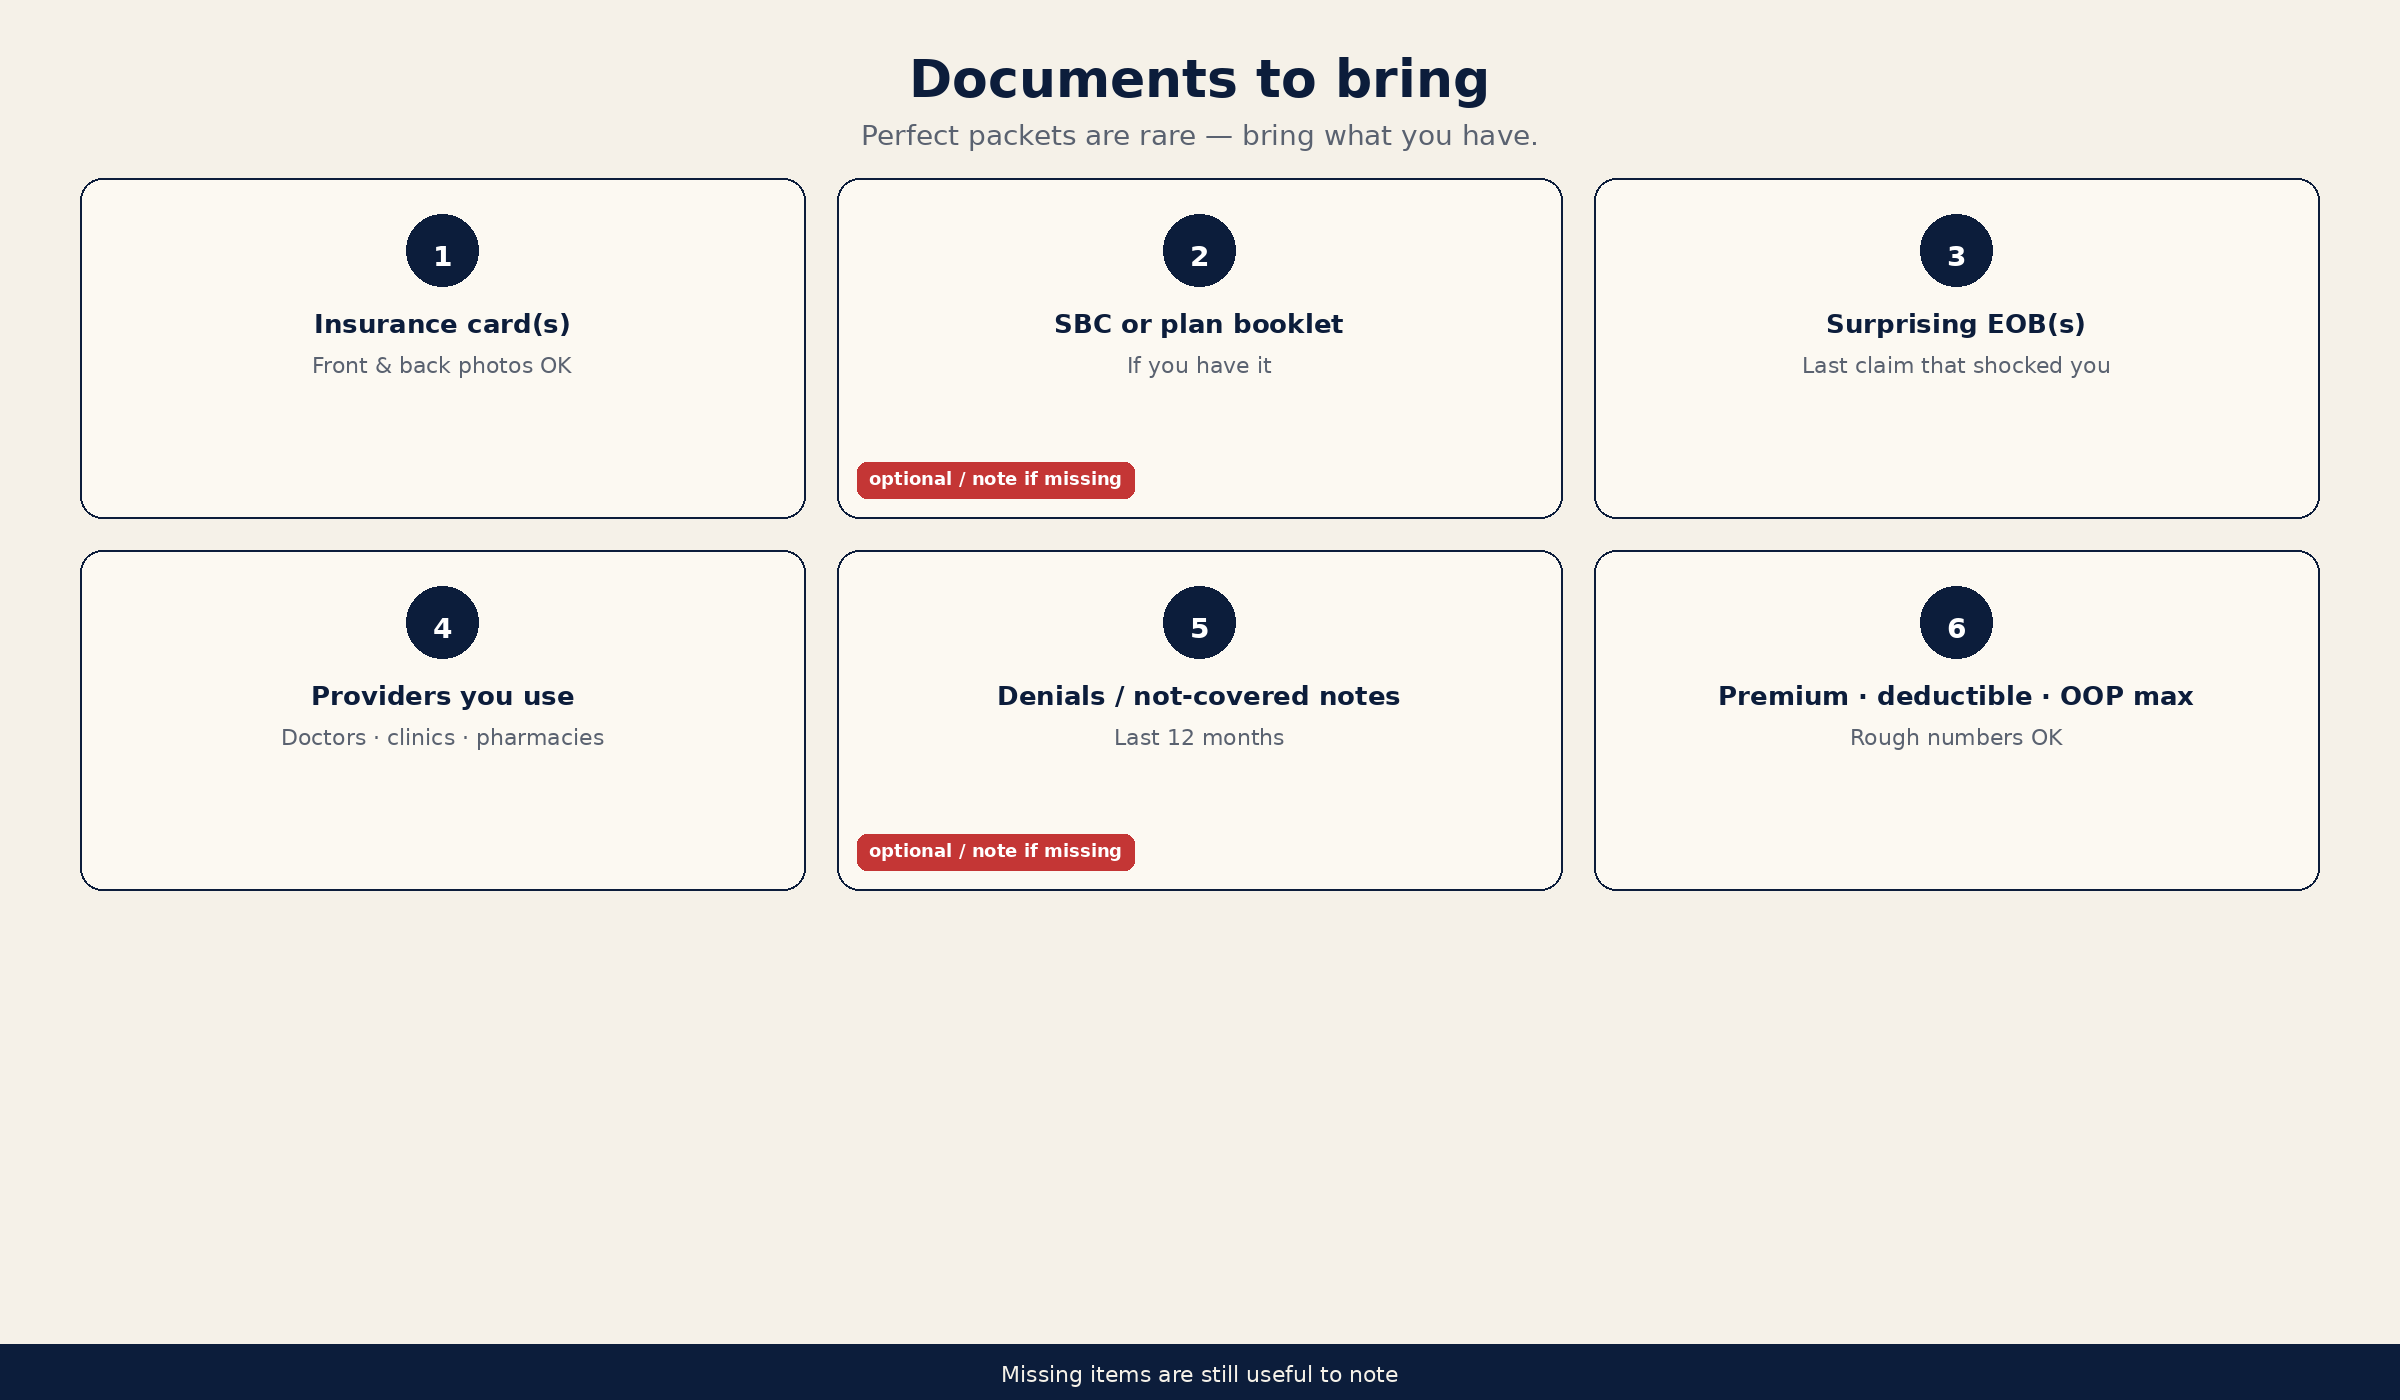
Before the review: what to gather
Bring what you have. Perfect packets are rare.
- Current insurance card(s) (front and back photos are fine)
- Most recent Summary of Benefits and Coverage (SBC) or plan booklet, if you have it
- Last Explanation of Benefits (EOB) for any claim that surprised you
- List of doctors, clinics, and pharmacies you actually use
- Any denial letters or "not covered" notes from the last 12 months
- Rough monthly premium and known deductible / out-of-pocket max
If something is missing, note that. Missing documents are data.
During the review: questions that force clarity
Ask these out loud. Write the answers in your own words.
- What does this plan protect me from? Ruin-level bills, routine care, or both?
- What do I pay before the plan pays? Deductible, copays, coinsurance.
- What counts toward the out-of-pocket max? And what never does?
- Are my people in network? Primary care, specialists, hospital, Rx. How to check each one yourself, before you pay, is in check your doctor, hospital and prescriptions before you buy.
- What happens after a serious claim? Who do I call, and what paperwork starts?
- What is outside this plan entirely? Dental, vision, gaps you already feel. Most adult health plans leave dental out; see does health insurance cover dental and vision?
- Is this major medical, or does it pay a fixed amount? A plan that pays a set sum per day in the hospital is not the same as one that pays the bill. The difference is in hospital indemnity insurance vs major medical.
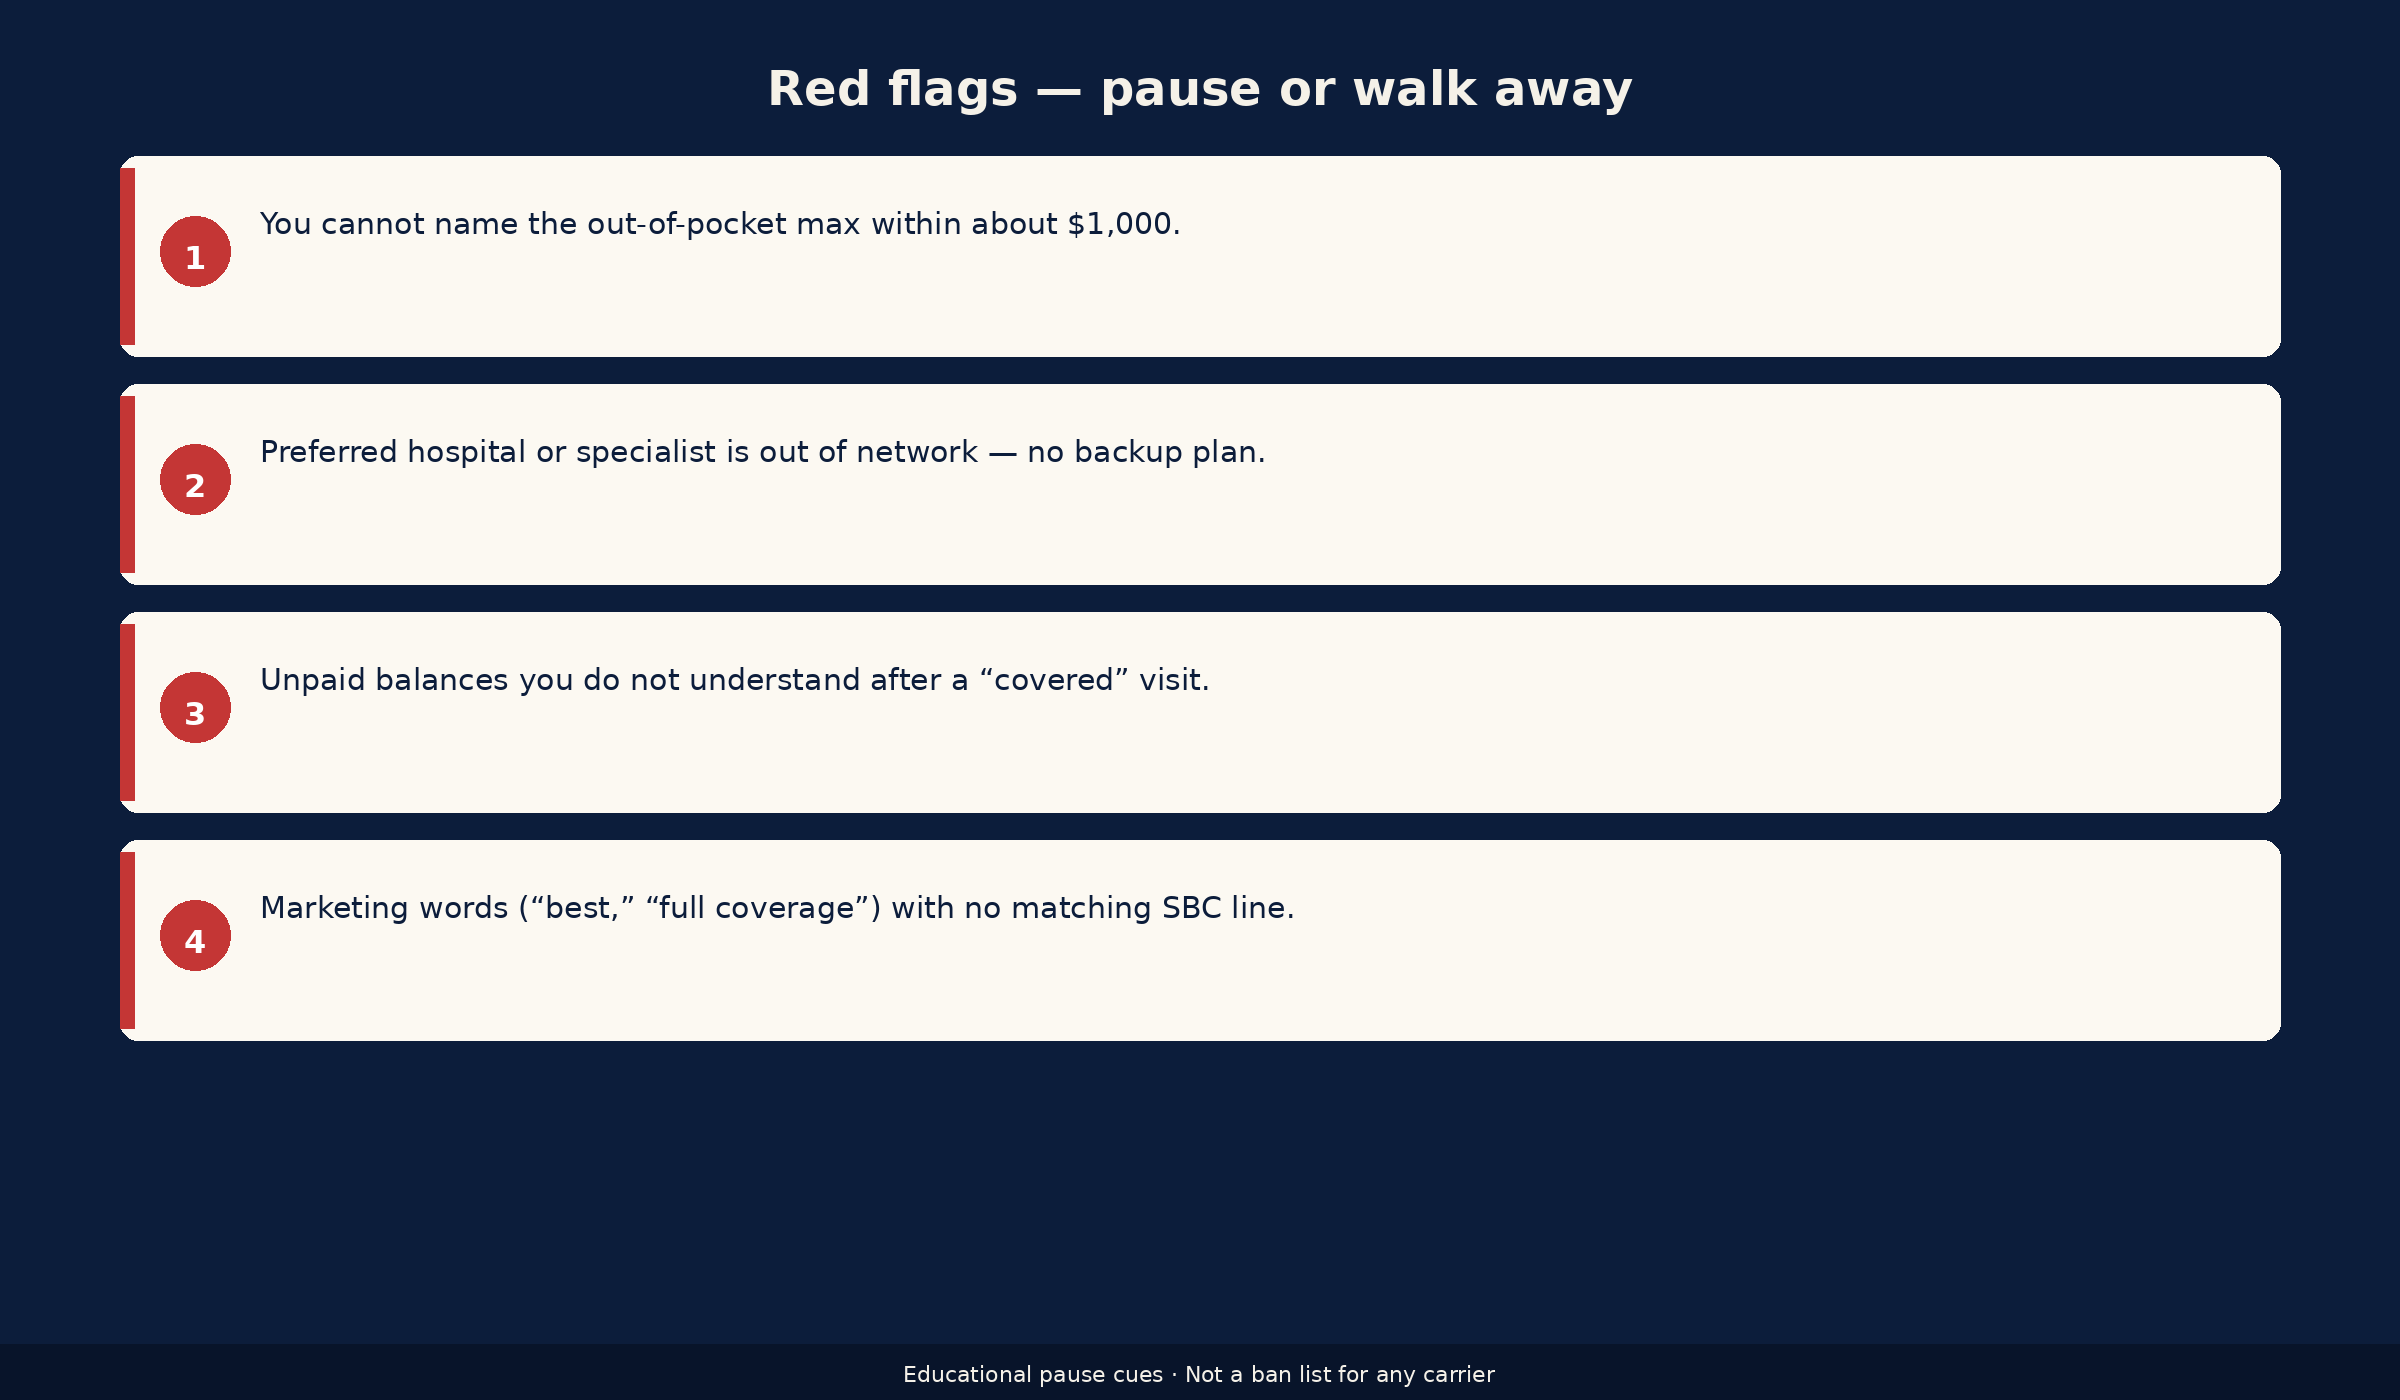
Red flags worth pausing on
- You cannot name the out-of-pocket max within $1,000.
- Your preferred hospital or specialist is out of network with no backup plan.
- You have unpaid balances you do not understand after a "covered" visit.
- Marketing language ("best," "full coverage") with no matching SBC line.
After the review: how to leave the conversation
A useful review ends with three outputs:
- A one-sentence household rule ("This stack is for X; it is not for Y").
- A short list of open questions still needing documents or carrier answers.
- A dated next step (call carrier, request SBC, schedule follow-up).
Unclear answers are often underinsurance signals. See what underinsured means.
Circle your next window on the OE and Medicare AEP calendar before you leave the review.
Related research
- Browse the research library.
- Start with what underinsured means.
- Map stack design in catastrophic core + gap.
- Circle deadlines on the OE and Medicare AEP calendar.
- Shopping for 2027? Read 2027 Open Enrollment dates, deadlines and what changed.
- Verify a confusing offer using medical insurance scams.
FAQ
What should I bring to a healthcare review?
Bring cards, SBC or booklet if you have it, surprising EOBs, your real provider list, recent denials, and known premium / deductible / out-of-pocket numbers. Missing items are still useful to note.
What questions should I ask during a review?
Ask what the plan protects you from, what you pay first, what counts toward the out-of-pocket max, whether your providers are in network, what happens after a serious claim, and what sits outside the plan.
When should I pause or walk away?
Pause if you cannot name the out-of-pocket max, your key providers are out of network with no plan, unpaid balances are unexplained, or marketing claims do not match the SBC.
Is this checklist the same as booking a free healthcare review?
No. This page is the educational checklist. A free healthcare review is the conversation if you want someone to walk it with you.
Next step
Book a free healthcare review if you want someone to walk this checklist with you. No obligation to buy anything in that conversation.
Prefer a guided walkthrough? Start a free healthcare review.
More plain-English guides live in the research library.
For shorter articles and news, browse Resources.
See how AFHC works with families on Our services.
Medicare timing and product basics: Medicare.