Who we help
What is catastrophic health coverage, and who should buy it?
Catastrophic health coverage means two things: the ACA catastrophic plan on HealthCare.gov, which only people under 30 or with a hardship exemption can buy, and catastrophic-first coverage, which any adult can build from a high-deductible core plus gap coverage. It fits healthy households that can pay for routine care in cash and want the six-figure bill covered. Educational, every rule linked to its source.
Catastrophic health coverage is insurance built to pay the large, rare medical bill, the hospitalization or serious illness that would otherwise change a household's finances, while you pay for routine care yourself. On HealthCare.gov the phrase names a specific Marketplace plan category that only people under 30 or with a hardship exemption can buy. For every other adult it describes a way of building coverage: a high-deductible core, sometimes with a supplemental gap layer, chosen by a healthy household that would rather bank the premium than pre-pay for doctor visits.
This page covers both meanings, exactly as the government defines the first and as America First Healthcare practises the second. It is educational, not personalized insurance advice, and every eligibility statement links to its source.
What is catastrophic health coverage?
Type "catastrophic health insurance" into a search box and you are asking one of two questions with different answers.
The regulatory meaning. On HealthCare.gov, a catastrophic plan is a specific Marketplace plan category. It has the lowest premiums and a very high deductible, and it is only available to people under 30 or to people who qualify for a hardship or affordability exemption (HealthCare.gov, catastrophic health plans).
The everyday meaning. Most adults typing that phrase mean something plainer: "Cover me for the bill that would ruin us. I will pay for the small stuff." That is not a plan category. It is a way of building coverage, and it is the thinking behind America First Healthcare's own framework, described in gap insurance and the catastrophic core + gap layer.
Who is catastrophic coverage for?
Catastrophic-first coverage fits a household that:
- barely sees a doctor in a normal year and would rather bank the premium than pre-pay for visits;
- can cover routine care and the deductible from cash if a bad year comes;
- has no diagnosis in the household that an underwritten plan would exclude, or is willing to keep a guaranteed-issue Marketplace plan as the core;
- fears the six-figure bill, not the $150 office visit.
It does not fit a household with a chronic condition that will hit the deductible every year and has no cash buffer, anyone planning a pregnancy on a non-ACA product, or anyone who would use a supplemental gap policy as their only coverage.
How catastrophic coverage works
For the arithmetic of a high-deductible year, see deductible, copay, coinsurance and out-of-pocket max, with examples.
The ACA catastrophic plan: who qualifies
HealthCare.gov lists two groups who can enroll in a catastrophic plan (source):
- People under 30 years old.
- People of any age who qualify for a hardship exemption or an affordability exemption.
Hardship exemptions are tied to specific circumstances such as homelessness, eviction or foreclosure, a utility shut-off notice, domestic violence, medical debt, or a natural disaster. They generally cover the month before, the months of, and the month after the hardship, extendable up to a full calendar year in some cases. There is no exemption for being unemployed on its own (HealthCare.gov, hardship exemptions).
The ACA catastrophic plan: what it covers
More than the name suggests. HealthCare.gov defines it as a plan that meets all the requirements of other qualified health plans but "doesn't cover any benefits other than 3 primary care visits per year before the plan's deductible is met" (HealthCare.gov glossary). In practice that means:
- All ten essential health benefits, including hospitalization, emergency care, maternity, mental health and substance use treatment, and prescription drugs. HealthCare.gov states this is true for every Marketplace category, "including Catastrophic plans" (HealthCare.gov, what Marketplace plans cover).
- Preventive services at no cost, and at least three primary care visits per year before you meet the deductible.
- Full protection for pre-existing conditions: no Marketplace plan can reject you, charge you more, or refuse to pay essential health benefits for a condition you had before coverage started (HealthCare.gov).
Everything else counts toward a very high deductible until you reach it, and after the out-of-pocket maximum the plan pays for covered in-network care (HealthCare.gov, out-of-pocket maximum).
Why most adults could not buy the ACA catastrophic plan, and what changed for 2026
Because of the age rule. Once you turn 30, the only door is a hardship or affordability exemption, and until 2025 those were tied to documented circumstances such as eviction or medical debt, not to wanting a cheaper plan.
For the 2026 plan year that door widened. On September 4, 2025, CMS issued hardship-exemption guidance for consumers "who find themselves ineligible for advance payments of the premium tax credit (APTC) or cost-sharing reductions (CSRs) due to their projected annual household incomes." Generally, consumers newly ineligible because their income is below 100 percent or above 400 percent of the federal poverty level "will be eligible for a hardship exemption and can enroll in catastrophic coverage," on or off the exchange, and from November 1, 2025 the HealthCare.gov application evaluates that eligibility automatically from the income you report (CMS fact sheet, September 4, 2025). The guidance applies in HealthCare.gov states and participating state exchanges. Exemption rules can change by regulation or court decision between plan years, so confirm that the exemption still applies when you file the application, either in the HealthCare.gov eligibility result or with a licensed agent, before relying on it.
There is a second reason HealthCare.gov itself gives for looking elsewhere even if you qualify: if you are eligible for the premium tax credit or cost-sharing reductions, the site says "a Bronze or Silver plan may be a better value" (HealthCare.gov). The credit lowers those plans' premiums; the catastrophic plan's sticker price can end up higher than a subsidized Bronze plan's actual price.
So for a 35-year-old freelancer, a 48-year-old couple, or a 61-year-old waiting for Medicare, the first question is now whether your income puts you outside the premium tax credit. If it does, ask the Marketplace application for the catastrophic plan. If it does not, or if no catastrophic plan is sold in your county (HealthCare.gov notes they "might not be available in all areas"), what follows is.
Catastrophic-first coverage for everyone else
The goal is the same: pay for the bill that would change your life, accept more responsibility for routine costs. Four product types get used, alone or stacked. Read the "never pays" line of each one.
A Marketplace Bronze or high-deductible plan. The closest legal equivalent to a catastrophic plan for someone over 30. HealthCare.gov defines a high-deductible health plan as one with a higher deductible than a traditional plan, usually with a lower monthly premium, and notes that it can be combined with a health savings account (HealthCare.gov glossary). The IRS sets the deductible and out-of-pocket limits a plan must meet to be HSA-eligible each year (IRS Publication 969). Pays for: all ten essential health benefits after the deductible, preventive care before it, with a capped out-of-pocket maximum and full pre-existing condition protection. Never pays for: out-of-network care in most designs, anything not in the plan's covered benefits, and, until the deductible is met, most routine care. Not right for: a household with a chronic condition that will hit the deductible every year and has no cash buffer; a Silver plan with cost-sharing reductions may cost less in total.
Private major-medical coverage outside the Marketplace. Some carriers sell individual major-medical and related plans off the exchange. Depending on the product and state, these use medical underwriting: health questions at application, with the possibility of a decline, a higher rate, or an exclusion rider for a condition you already have. Some are not ACA-compliant and need not cover all ten essential health benefits. Pays for: the covered services listed in the policy, often with a broad choice of providers and a deductible you select. Never pays for: excluded pre-existing conditions, benefits the policy does not list (maternity and mental health are common gaps in non-ACA products), and anything after a benefit maximum if the policy has one. Not right for: anyone with a serious diagnosis in the household, anyone planning a pregnancy, anyone who relies on an ongoing prescription the policy does not list, and anyone who qualifies for a meaningful premium tax credit, which cannot be used off-exchange (HealthCare.gov, premium tax credit). Our private health insurance plans page walks through this path in detail.
Short-term medical. Temporary coverage for a limited number of months. Duration and renewal rules vary by state. Medically underwritten, not ACA-compliant. Pays for: the covered services listed in the policy during its term, typically after a deductible. Never pays for: pre-existing conditions, essential health benefits the policy excludes, and anything after the term ends. A diagnosis during the term may make the next term unavailable. Not right for: anyone who needs coverage for more than a bridge period, or who has any condition that could be called pre-existing.
Supplemental gap coverage. Accident, critical illness, and hospital indemnity policies pay a fixed or scheduled amount when a defined event happens. They are supplements, not health insurance, and do not replace a core plan. Pays for: the scheduled amount for the named event, often directly to you. Never pays for: the hospital's full bill, events not named in the schedule, and commonly pre-existing conditions for a waiting period or entirely. Not right for: anyone who would use it as their only coverage. Stacked on a high-deductible core, it can cover the deductible-sized gap; alone it leaves the ruin risk open, the condition described in What "underinsured" means.
What changed for 2026
Four things moved, and together they explain why catastrophic-first coverage is back in more households' comparisons.
- The enhanced premium tax credits expired at the end of 2025. The National Association of Insurance Commissioners warned in October 2025 that the enhanced subsidies were "scheduled to end after 2025" and that Marketplace premiums "could be much higher in 2026" (NAIC, what are my health plan options for 2026). Insurers raised Marketplace premiums an estimated 26% on average for 2026 (KFF).
- CMS opened catastrophic plans to adults who lose subsidy eligibility because of income, through the hardship exemption described above (CMS, September 4, 2025).
- The 2026 out-of-pocket limit, which is also the ACA catastrophic plan's deductible, is $10,600 for an individual and $21,200 for a family (CMS plan year 2026 fact sheet).
- HSA limits rose. For 2026 an HSA-eligible high-deductible plan needs a deductible of at least $1,700 self-only or $3,400 family, with out-of-pocket limits of $8,500 and $17,000, and the contribution limits are $4,400 and $8,750 (IRS Revenue Procedure 2025-19). HealthCare.gov states that all Bronze and Catastrophic plans work with a health savings account (HealthCare.gov).
What does catastrophic health coverage cost?
This page does not quote premiums. The factors tell you which questions to ask.
- Age, location, tobacco use, household size, and metal tier are the only factors Marketplace plans may use. Health and gender are prohibited (HealthCare.gov).
- Health history and the deductible you choose are the big drivers for underwritten private plans.
- The premium tax credit, if you qualify, applies only to Marketplace plans and can reverse the sticker-price comparison.
- The deductible on an ACA catastrophic plan is set at the annual out-of-pocket limit for the plan year. For 2026 that limit is $10,600 for an individual and $21,200 for a family (HealthCare.gov, out-of-pocket maximum).
- The total in a bad year is premium plus deductible plus anything excluded. A low premium with an uncapped exclusion is not cheap. Ask for the out-of-pocket maximum and the exclusion list before the premium.
Catastrophic coverage: pros and cons
Advantages
- The lowest monthly premium of any structure, because you are not pre-paying for routine care.
- On an ACA catastrophic, Bronze or high-deductible plan: all ten essential health benefits, free preventive care, a capped out-of-pocket maximum, and full pre-existing condition protection.
- A high-deductible plan that meets IRS limits can be paired with a health savings account.
- Routine care paid in cash is often cheaper than the same care billed through a carrier, and you choose the provider.
Drawbacks
- A very high deductible: until you reach it you pay for nearly everything except preventive care (what counts as preventive) and, on the ACA catastrophic plan, three primary care visits.
- Most adults cannot buy the ACA catastrophic plan at all.
- If you qualify for the premium tax credit, a subsidized Bronze or Silver plan may cost less in total than a catastrophic plan.
- Private and short-term products are medically underwritten, may exclude pre-existing conditions, and may not cover maternity or mental health.
- A supplemental gap policy used alone is not health insurance.
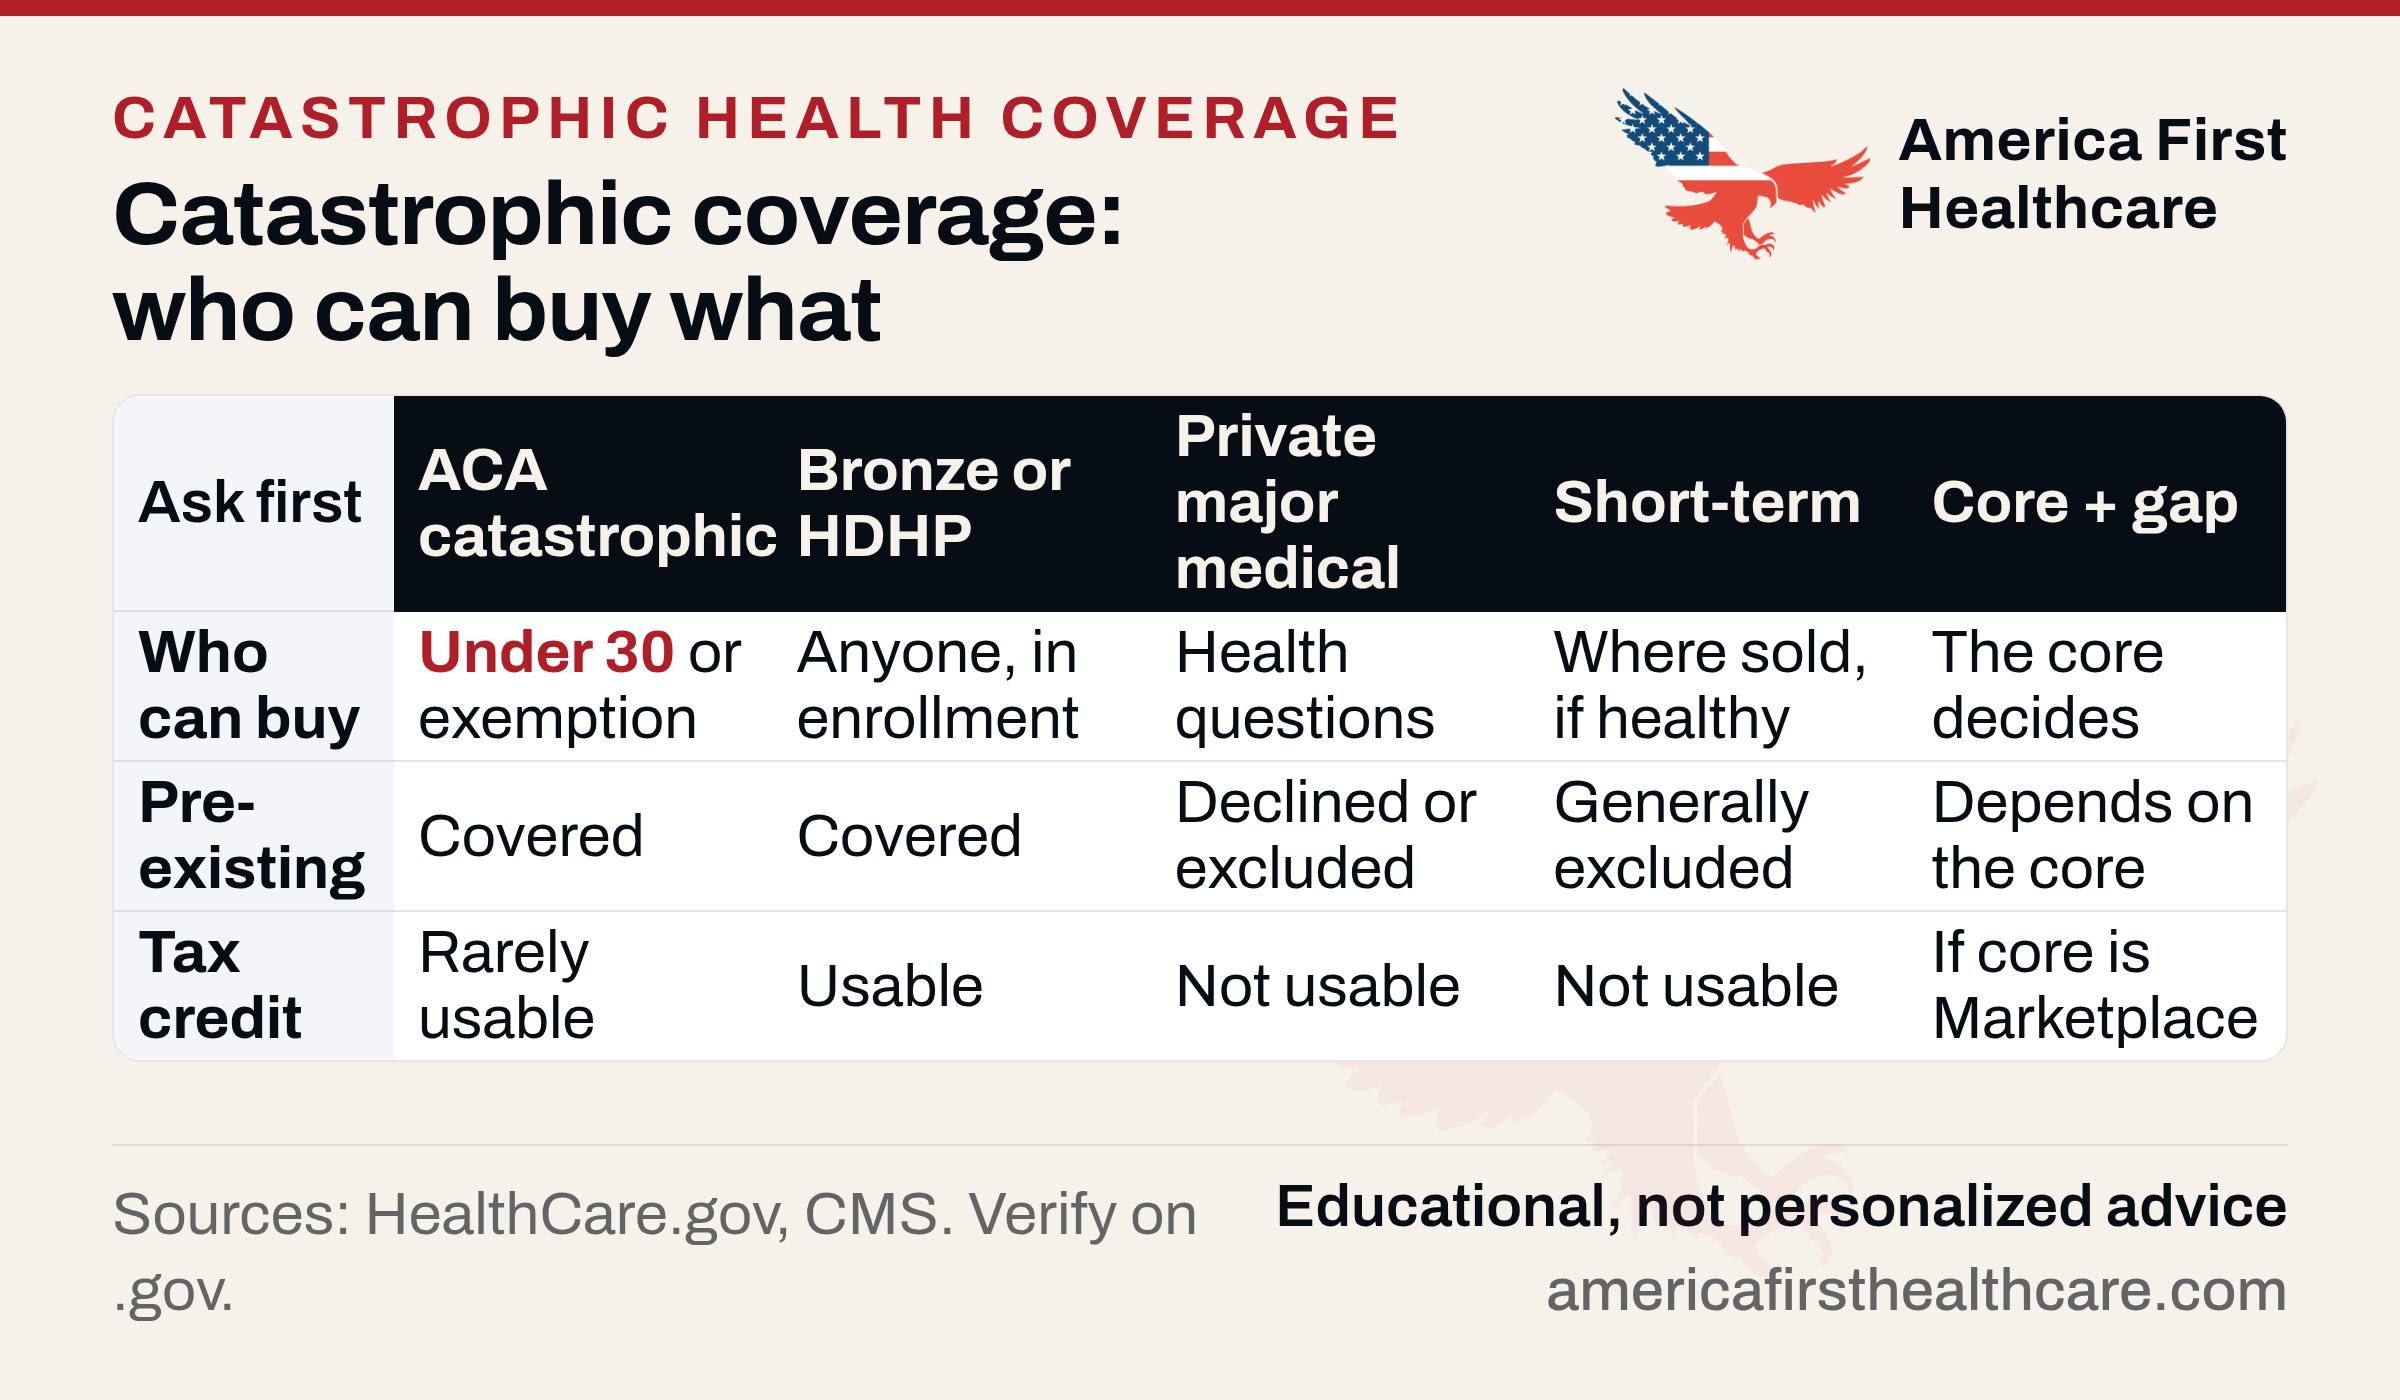
How catastrophic coverage compares to the alternatives
| ACA catastrophic plan | Marketplace Bronze / HDHP | Private major-medical | Short-term medical | Catastrophic core + gap layer | |
|---|---|---|---|---|---|
| Who can buy it | Under 30, or hardship exemption | Anyone, during open or special enrollment | Anyone who passes underwriting | Anyone who passes underwriting, where sold | Anyone; the core decides eligibility |
| Pre-existing conditions | Covered | Covered | Can be declined, rated or excluded | Generally excluded | Depends on the core; gap products commonly exclude |
| Essential health benefits | All ten | All ten | Only what the policy lists | Only what the policy lists | Depends on the core |
| Premium tax credit | Not usable in practice for most | Usable | Not usable | Not usable | Usable only if the core is a Marketplace plan |
| Routine care | Three primary care visits, then deductible | After deductible | After deductible you choose | After deductible | Cash prices, plus scheduled gap payments |
| The six-figure bill | Covered after the out-of-pocket maximum | Covered after the out-of-pocket maximum | Covered up to any benefit maximum | Covered during the term only | Covered by the core; the gap layer helps with the deductible |
A fixed-benefit hospital policy is not catastrophic coverage; see hospital indemnity insurance vs major medical.
Catastrophic health insurance by age: over 30, 40, 50 and 60
The catastrophic-first idea is the same at every age. What changes is price, underwriting, and the length of the road to Medicare.
Over 30
You have just aged out of the ACA catastrophic plan. Marketplace Bronze and high-deductible plans are the direct replacement, and if your income qualifies, the premium tax credit can make a Bronze plan cost less than the catastrophic plan would have. Underwritten private plans are at their most accessible at this age. The caveat is the pre-existing condition rule above: it does not get more forgiving as you age.
Over 40
Premiums rise with age in every market. On the Marketplace, federal rules allow premiums to be up to three times higher for older adults than for younger ones (HealthCare.gov, how plans set your premiums); underwritten products price age their own way. Households in their forties are also more likely to carry a diagnosis, which pushes the comparison toward guaranteed-issue Marketplace coverage. Whether a high-deductible plan is still right depends on the cash buffer, not the birthday.
Over 50
The answer needs to be direct. The ACA catastrophic plan is not available to you without an exemption. Underwriting gets stricter: more conditions are declinable, exclusion riders are more common, and rates are higher. A Marketplace Bronze or high-deductible plan with pre-existing condition protection is the default core for many households at this age, with gap coverage layered where the deductible is the fear. Anyone promising an underwritten plan "with no health questions" should put the product category in writing.
Over 60, before Medicare
Medicare eligibility generally begins at 65, and HealthCare.gov is explicit that Medicare is not part of the Marketplace and that it is against the law for someone who knows you have Medicare to sell you a Marketplace plan (HealthCare.gov, Medicare and the Marketplace). Until then, you are buying a bridge. If you left employer coverage, COBRA may run for up to 18 months at up to 102 percent of the plan's full cost where the employer had 20 or more employees (U.S. Department of Labor, COBRA FAQs), and losing coverage opens a 60-day Special Enrollment Period on the Marketplace (HealthCare.gov). The bridge years, income planning for the premium tax credit, and the Medicare handoff are covered in more depth on Health insurance for early retirees.
Catastrophic health insurance in Florida and Texas
Florida and Texas produce a large share of state-specific searches for this term. The rules on this page are federal and apply in both: the ACA catastrophic plan's age and exemption limits, the essential health benefits, the pre-existing condition protections, and the Special Enrollment window. What differs by state is which non-ACA products are offered and how long a short-term plan may run. Our health insurance in Florida page lists the Marketplace, the enrollment dates and the short-term rules for our home state. If you live in either state and want to know what is actually sold there, contact us and ask.
What to look for when reviewing catastrophic coverage options
Whatever the product is called, read these seven things in the policy documents before the premium:
- Product class, in writing. ACA catastrophic plan, Marketplace Bronze, off-Marketplace ACA-compliant, underwritten major medical, short-term, or fixed indemnity. Each has different rules on pre-existing conditions and benefits.
- The out-of-pocket maximum, and whether out-of-network care counts toward it. This is the number that defines "catastrophic."
- Any benefit maximum. Some non-ACA policies stop paying after a lifetime or per-cause amount. A cap below the cost of a serious hospitalization defeats the purpose.
- Pre-existing condition treatment. Covered, excluded for a waiting period, or excluded by rider.
- The ten essential health benefits, especially hospitalization, prescription drugs, maternity and mental health.
- The network, checked by the name of the hospital you would actually go to.
- Renewability. Whether the carrier can decline to renew after a claim, and what happens to the rate.
If a pregnancy is possible, see which health plans cover pregnancy and birth.
Where to get help choosing a catastrophic health plan
HealthCare.gov's Find Local Help directory lists two kinds of Marketplace-certified help and explains the difference. Assisters and Navigators are "required to provide fair, impartial, and accurate information" and cannot sell you anything. Agents and brokers are licensed to sell Marketplace plans in their state, are "generally paid by insurance companies whose plans they represent," are "required in many states to act in your best interest," and may not sell plans from companies they do not represent. Either can enroll you with any subsidy you qualify for, as long as the enrollment goes through the Marketplace. Your state department of insurance can verify any agent's license and, the NAIC notes, help you find licensed agents or certified assisters.
America First Healthcare is an independent licensed agency. Our review of catastrophic-first options is free, compares a Marketplace quote at your income with private options, and ends with a written recommendation, including "keep what you have" or "take the subsidised Bronze plan" when that is the answer. Questions to put to us or anyone else are in how to choose a private health insurance plan.
How to decide
The healthcare review checklist walks the questions in order: name the bill that would break you, list every diagnosis and prescription in the household, estimate this year's income, check your doctors against each network, and only then compare the bad-year total rather than the monthly premium. The private health insurance plans page describes how America First Healthcare builds a core-plus-gap stack around those answers, and Private health insurance vs Obamacare compares the two most common cores side by side.
FAQ
What is catastrophic health insurance?
It means two different things. On HealthCare.gov it is a specific Marketplace plan category with low premiums, a very high deductible, and eligibility limited to people under 30 or those with a hardship or affordability exemption (source). In everyday use it means any coverage built to pay for the large, rare medical bill while you pay routine costs yourself.
What does an ACA catastrophic plan cover?
The same ten essential health benefits as every other Marketplace plan, preventive services at no cost, and at least three primary care visits per year before the deductible (source). Everything else applies to the deductible until you reach it.
Can I get catastrophic health insurance over 50?
Not the ACA catastrophic plan, unless you qualify for a hardship or affordability exemption (source). Adults over 50 who want catastrophic-first coverage usually look at a Marketplace Bronze or high-deductible plan, a private major-medical plan that uses medical underwriting, or a combination of a high-deductible core and supplemental gap coverage.
Does catastrophic coverage cover pre-existing conditions?
An ACA catastrophic plan does: no Marketplace plan can reject you or charge more for a pre-existing condition (source). Medically underwritten private plans can decline you, charge more, or exclude the condition. Fixed-benefit gap products commonly exclude pre-existing conditions for a period or entirely.
What is the difference between a catastrophic plan and a high-deductible health plan?
A catastrophic plan is a Marketplace category with age or exemption limits. A high-deductible health plan is any plan with a higher deductible than a traditional plan, available at any age, and if it meets IRS limits it can be paired with a health savings account (HealthCare.gov glossary; IRS Publication 969).
Is catastrophic coverage the same as gap insurance?
No. Catastrophic coverage is the core: the plan that pays the large hospital bill after a deductible. Gap insurance is a supplement stacked on top, such as an accident, critical illness or hospital indemnity policy that pays a fixed amount toward the deductible-sized gap. Gap coverage alone is not health insurance and leaves the ruin risk open. See gap insurance and the catastrophic core + gap layer.
Can I buy a catastrophic health plan if I am over 30 in 2026?
Possibly, through a hardship exemption. In September 2025 CMS issued guidance that consumers who are ineligible for the premium tax credit or cost-sharing reductions because of their projected income, generally below 100% or above 400% of the federal poverty level, qualify for a hardship exemption and can enroll in a catastrophic plan on or off the exchange, with eligibility evaluated automatically in the HealthCare.gov application from November 1, 2025 (CMS). Without that exemption, the under-30 rule still applies. Check HealthCare.gov for the current rule when you apply.
Where can I get help choosing a catastrophic health plan?
HealthCare.gov's Find Local Help directory lists Marketplace-certified assisters, who must give impartial help and cannot sell you anything, and licensed agents and brokers, who are generally paid by the insurance companies whose plans they represent (HealthCare.gov). Your state department of insurance can verify any agent's license. America First Healthcare, an independent licensed agency, reviews catastrophic-first options for free and will tell you if a subsidised Marketplace plan is the better deal.
Key takeaways
- Catastrophic health coverage is insurance built to pay the large, rare medical bill while you pay for routine care yourself.
- The ACA catastrophic plan on HealthCare.gov covers all ten essential health benefits and pre-existing conditions, but only people under 30 or with a hardship or affordability exemption can buy it. For 2026, CMS extended that exemption to adults whose income makes them ineligible for the premium tax credit.
- Every other adult builds catastrophic-first coverage from a core, usually a Marketplace Bronze or high-deductible plan or an underwritten private major-medical plan, sometimes with supplemental gap coverage stacked on top.
- It fits healthy households with a cash buffer that fear the six-figure bill; it does not fit households with a chronic condition and no buffer, anyone planning a pregnancy on a non-ACA product, or anyone who would rely on a gap policy alone.
- Compare the total in a bad year, premium plus deductible plus exclusions, and check the pre-existing condition rule before the monthly price.
- America First Healthcare's free review names your household's ruin risk and checks whether your current plan actually covers it.
Next step
If you want help naming your household's ruin risk and checking whether your current plan actually covers it, start a free healthcare review. It is a conversation, not a hard sell.
More plain-English guides live in the research library.
Availability by state
Plan availability and rules vary by state. Tell us your state and a licensed advisor will walk through what is actually available there.